News
General
13 views
What is liquidation preference in a term sheet?
Oct 16, 2026
📍 Phliadelphia,PA, USA
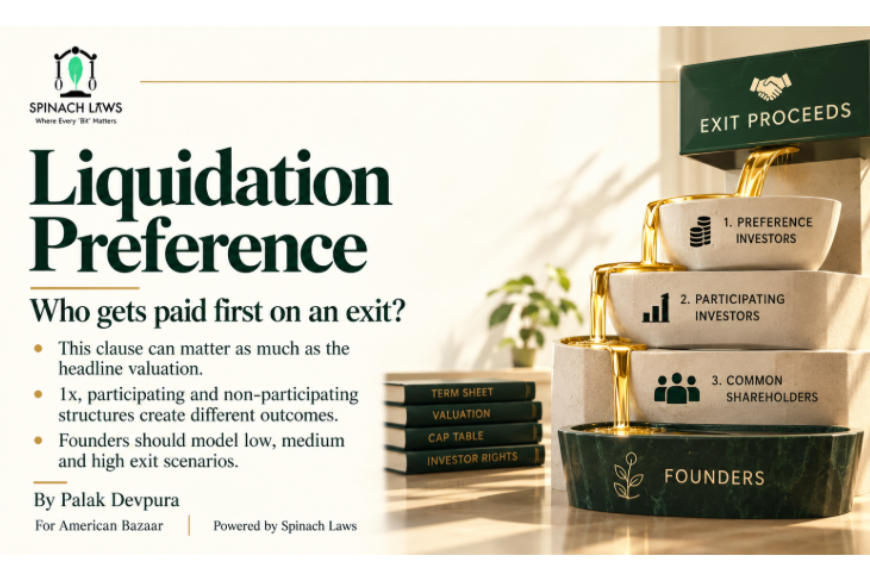
# Liquidation Preference: The Term Sheet Clause Founders Should Never Overlook
When a founder receives a term sheet valuing a startup at ₹100 crore, the valuation often becomes the main focus of negotiations. Investors, however, may pay equal attention to another provision that can significantly affect the distribution of money when the company is sold: liquidation preference.
Liquidation preference determines the order in which investors and other shareholders receive proceeds following certain liquidity events. Depending on the agreement, these events may include a company liquidation, acquisition, merger or another specified exit. As a result, the ownership percentage shown on paper does not always reflect the amount a shareholder will ultimately receive.
Consider a simple example. An investor puts ₹10 crore into a startup in exchange for a 20% stake, with a 1x non-participating liquidation preference. If the company is subsequently sold for ₹30 crore, the investor would generally compare two options: receive the ₹10 crore preference amount or convert the investment into equity and take 20% of the sale proceeds, amounting to ₹6 crore. Assuming sufficient proceeds and no competing senior claims, the investor would typically choose the ₹10 crore preference, leaving ₹20 crore for the other shareholders.
Now consider a sale at ₹100 crore. A 20% equity stake would be worth ₹20 crore, making conversion more attractive than receiving only the ₹10 crore preference amount. This illustrates how the economics of a liquidation preference can change depending on the company's exit value.
The example reflects a basic non-participating structure, in which the investor generally chooses between the preference amount and the proceeds available through conversion into equity. Participating liquidation preference can produce a different outcome. Under such an arrangement, an investor may recover the preference amount first and then receive an additional share of the remaining proceeds, subject to the contract's terms. A preference multiple, such as 2x, can increase the amount recoverable before other shareholders receive their share.
The precise drafting therefore matters. Small differences in the terms can produce substantially different outcomes for founders, employees holding equity and other shareholders.
Investors seek liquidation preference because venture capital involves significant uncertainty. They often invest substantial sums in exchange for minority ownership in businesses whose future value is difficult to predict. A preference can provide a measure of downside protection when an exit delivers less than anticipated, although the actual recovery depends on the available proceeds, the rights of other investors and the applicable agreement.
In India, compulsorily convertible preference shares, commonly known as CCPS, are frequently used in venture capital transactions. These instruments can include preferential economic rights, including liquidation preference, subject to applicable corporate law, securities requirements and foreign investment regulations where relevant.
For founders, the objective should not be to reject liquidation preference outright, but to understand precisely how it affects the distribution of exit proceeds. The first questions to ask are whether the preference is 1x or a higher multiple, whether it is participating or non-participating, and which events trigger its application.
Founders should also examine whether dividends accrue and are added to the preference amount, how different funding rounds rank against one another, and whether later investors receive priority over earlier investors. These details can determine how much money remains for founders and other shareholders after investor claims are satisfied.
Financial modelling is particularly important. Founders should calculate the distribution of proceeds under low, medium and high exit scenarios rather than assessing the clause solely against an optimistic valuation. A preference that appears manageable in a large acquisition could materially reduce the founder's payout in a smaller sale.
The analysis should also account for the company's capital structure, including other preference shares, debt obligations and contractual rights that may affect the available proceeds. A simple ownership calculation may be insufficient when multiple funding rounds have different economic protections.
Ultimately, a startup's valuation describes its agreed or implied worth at a particular point in time, while liquidation preference can influence how the proceeds from a future exit are divided. For founders negotiating a term sheet, understanding both is essential to evaluating the true economic cost of raising capital.
Tags
news
Comments (0)
Login to post comments
No comments yet
Be the first to share your thoughts about this post.